
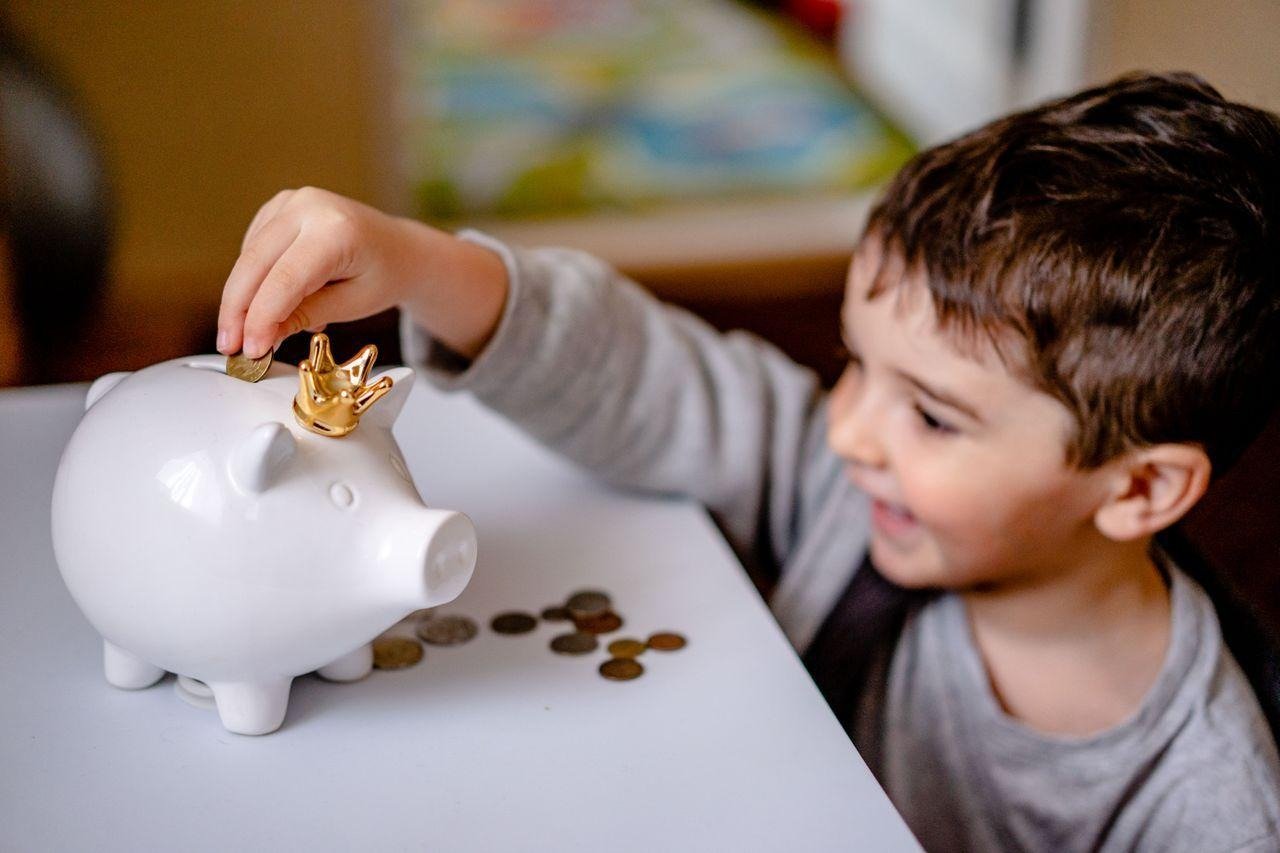
Setting money aside for a child’s early education often feels like a moving target. Between monthly groceries, utilities, mortgage payments, and surprise home repairs, family budgets get squeezed from every angle. Before you know it, the savings fund you earmarked for early learning programs, daycare fees, or enrichment activities keeps getting tapped to cover everyday expenses.
The tricky part is that budget leaks aren’t always big, flashy splurges. More often, they are small, unexamined household habits that slowly drain your cash reserves over time. Here are five costly budgeting mistakes parents make that quietly eat away at early education funds—and how to fix them.
1. Treating Subscriptions and Auto-Renews as “Set and Forget”
Digital subscriptions are one of the quietest cash drains in modern family budgeting. Between streaming platforms, meal kits, app subscriptions, and monthly subscription boxes, it’s remarkably easy to drop hundreds of dollars a month without realizing it.
Audit your bank and credit card statements every few months to flag recurring charges you no longer use. Canceling just two or three unused subscriptions can instantly free up an extra $50 to $100 a month. Funneling that reclaimed cash directly into an education high-interest savings account turns forgotten monthly expenses into meaningful long-term tuition growth.
2. Underestimating the Real Cost of Quality Early Childhood Programs
Many parents start planning for education expenses with university or college tuition in mind, completely overlooking the immediate costs of early childhood education. Quality early learning programs require real financial planning, but trying to cut corners on a child’s foundational development years often backfires.
Investing early in reputable learning environments—like a dedicated preschool Newmarket center like Leslie Street Daycare, which focuses on nurturing social skills and cognitive growth through play-based curriculum—sets children up for lifelong success. Factoring early childhood program costs into your household budget early prevents last-minute financial panic when registration season opens.
3. Relying on High-Interest Credit Cards to Cover Emergency Spikes
When a major appliance breaks down or a car needs emergency repairs, slipping the bill onto a high-interest credit card seems like the easiest quick fix. However, carrying balances with 20% or higher interest rates creates an ongoing debt trap that sucks up monthly cash flow for years.
Instead of putting emergency costs on revolving credit cards that erode your monthly savings capacity, exploring accessible alternative funding options makes much more sense. Many Canadian families look into direct installment loan solutions through online financial platforms like Lamina—a trusted direct lender with over 15 years of experience providing fast, predictable installment loans—to handle unexpected home expenses without jeopardizing long-term education funds.
4. Buying Everything Brand New for Rapidly Growing Kids
It’s completely natural to want the absolute best for your kids, but buying brand-new designer clothes, toys, and gear during their early growth spurts is a quick way to blow up a family budget. Toddlers grow out of shoe sizes and clothing sets in a matter of months, leaving behind closets full of gently worn items.
Embrace community buy-nothing groups, consignment shops, and secondhand marketplaces for clothing, toys, and play equipment. Saving 70% on everyday toddler gear leaves significantly more room in your monthly cash flow to deposit directly into an early education fund.
5. Keeping Savings in a Standard Low-Yield Account
Parking your child’s education money in a basic checking or low-yield savings account is an insidious mistake because inflation quietly erodes your purchasing power over time. When your money sits idle earning near-zero interest, you’re essentially losing value every month.